Freelancers increasingly work with clients in other countries, but international payment systems have not always kept pace with the global nature of independent work. Bank transfers can involve delays, intermediary fees, currency conversion costs, and additional compliance checks. Digital payment platforms may be convenient, but they can also impose fees, restrict availability, or delay withdrawals.
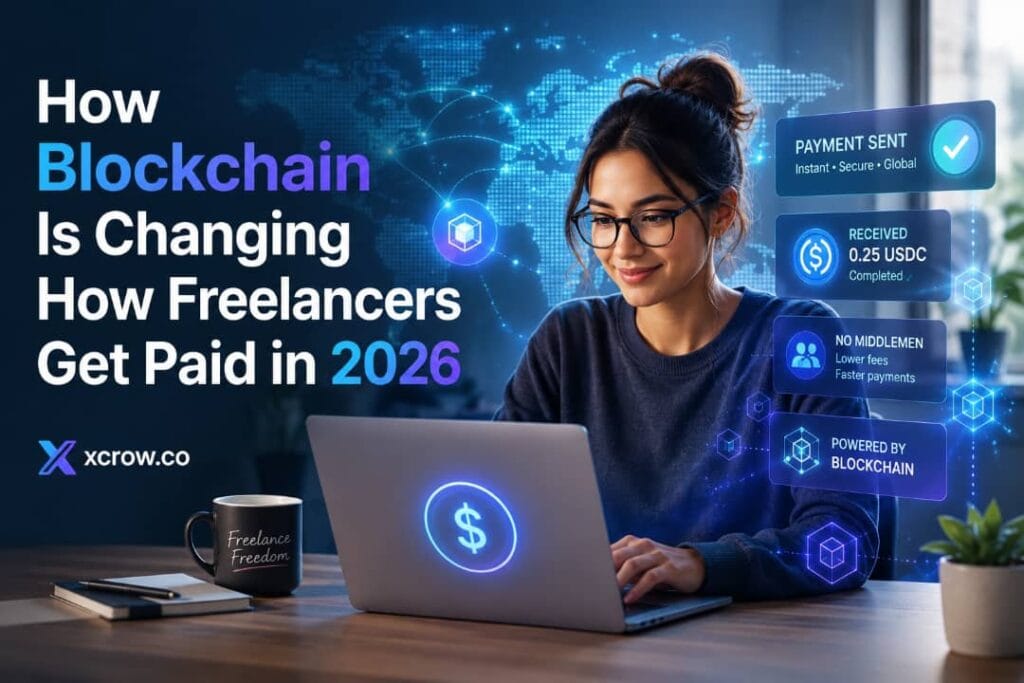
Blockchain-based payment networks offer another approach. They can record transfers on a shared ledger, move value across borders without relying on the same chain of correspondent banks, and support programmable arrangements such as digital escrow. These benefits are real, but they do not make every cryptocurrency payment automatically safe, cheap, or suitable. Freelancers need to understand both the opportunities and the risks.
What blockchain changes about a payment
A blockchain is a distributed record of transactions maintained by a network of computers. When a transfer is confirmed, the ledger records the movement of the digital asset between wallet addresses. Depending on the network, confirmation may take seconds, minutes, or longer during periods of congestion.
For a freelancer, the practical difference is that a client may be able to send a digital asset directly to a wallet rather than using several financial intermediaries. The transaction can be checked on the relevant network, and both parties can keep a record of the payment. This may be useful when traditional payment options are expensive, slow, or unavailable in a particular country.
Blockchain does not remove the need for identity checks, legal compliance, tax reporting, or responsible payment practices. It changes the payment rail; it does not change the underlying obligations of the client or freelancer.
Potential advantages for international freelancers
Faster settlement
Traditional international transfers may take several business days, especially when banks or payment providers perform manual reviews. A blockchain transfer can settle more quickly once it has been submitted and confirmed by the network. Faster settlement can help freelancers manage cash flow, particularly when they work with several international clients.
Access across borders
Some freelancers have limited access to international payment services because of local availability, account restrictions, or high minimum fees. A compatible blockchain wallet may provide an additional way to receive payment from a client in another country. Availability still depends on local law, exchange services, banking relationships, and the specific asset or network being used.
Transparent transaction records
Many public blockchains allow a user to verify a transaction using its wallet addresses and transaction reference. This can help both parties confirm whether funds were sent, received, or are still awaiting confirmation. A public transaction record does not replace a proper invoice or contract, but it can support payment reconciliation.
Programmable payment arrangements
Smart contracts are programs that execute predefined instructions on a blockchain. They can be used to support milestone payments, deposits, or escrow-like arrangements when the rules are carefully designed. For example, a client may fund a milestone and release payment after an agreed approval event.
Smart contracts are not automatically equivalent to a complete legal escrow service. Code may contain errors, an approval process may be unclear, and disputes may not be resolved simply because a payment rule is automated. A responsible arrangement should explain the deliverables, review period, dispute process, refund conditions, and what happens if either party fails to respond.
Stablecoins and cryptocurrency volatility
Freelancers who accept payment in Bitcoin, Ether, or another volatile asset may receive an amount worth more or less by the time they convert it. That risk can make pricing difficult for fixed-scope work. Stablecoins are digital assets designed to track the value of another asset, often a fiat currency such as the US dollar.
Stablecoins can reduce price volatility, but they are not risk-free. Their value may depend on reserves, issuer policies, market liquidity, the blockchain network, and local conversion options. A stablecoin may also be supported on several networks, and sending it through an incompatible network can result in a loss of funds.
Before accepting any digital asset, agree with the client on the asset, network, amount, payment deadline, transaction costs, and how the amount is valued. Put the details in the contract or invoice rather than relying on an informal message.
How freelancers can use blockchain payments responsibly
- Confirm legality and availability. Check the rules that apply in your country and the client’s country. Digital-asset restrictions, tax treatment, reporting requirements, and exchange rules vary.
- Use a written agreement. State the scope, price, currency or digital asset, wallet network, payment schedule, acceptance criteria, refunds, and dispute process.
- Test with a small amount. Confirm that the client is sending to the correct wallet and network before transferring a larger payment.
- Verify the address carefully. Blockchain transfers are often irreversible. Copy-and-paste malware and lookalike addresses create a serious risk.
- Protect wallet access. Use strong account security, enable multi-factor authentication where available, and store recovery information offline. Never share a private key or recovery phrase.
- Keep records. Save invoices, contracts, transaction references, exchange values, fees, conversion records, and dates. These records may be needed for accounting or tax reporting.
- Plan conversion and storage. Decide how funds will be converted to local currency, where they will be stored, and how exposure to price movements will be managed.
Blockchain payments versus traditional escrow
Blockchain payments and traditional escrow address related but different needs. A direct wallet transfer can move funds quickly, but it may not provide a practical way to reverse a mistake or resolve a disagreement. A conventional escrow service can hold funds under defined terms and may offer human review, dispute handling, refunds, and support.
The right option depends on the transaction, the client’s preferences, the level of trust between the parties, and the risks involved. For a small payment between experienced users, a direct transfer may be adequate. For a larger project with milestones, unclear deliverables, or parties who have not worked together before, a documented escrow arrangement may offer stronger protection.
Costs and risks to consider
Blockchain networks charge transaction fees, and those fees can change. Converting a digital asset into local currency may involve an exchange spread, withdrawal fee, or peer-to-peer risk. Some services also impose account, compliance, or processing charges.
Other risks include phishing, stolen credentials, fraudulent tokens, smart-contract vulnerabilities, mistaken network selection, lost wallet access, and regulatory changes. A transaction being visible on a public ledger does not prove that the sender is trustworthy or that the underlying project is legitimate.
Freelancers should also avoid promising clients that blockchain payments are anonymous, immune from compliance checks, or guaranteed to avoid taxes. Those claims can be inaccurate and may create legal or financial problems.
When blockchain payments may be useful
Blockchain payment options may be worth considering when both parties understand the technology, the asset and network are legally and practically available, the transfer cost is reasonable, and the freelancer has a secure way to store or convert the funds. They can be particularly useful for globally distributed technology teams and clients who already operate within digital-asset ecosystems.
They may be a poor fit when the client is unfamiliar with wallets, the transaction is subject to strict payment controls, the freelancer cannot safely secure the funds, or local conversion is unreliable. Offering several compliant payment options can be more practical than requiring every client to use cryptocurrency.
Final thoughts
Blockchain is changing freelance payments by providing new ways to transfer value, verify transactions, and automate parts of a payment arrangement. Its benefits include potential speed, broader access, transparent records, and programmable payment rules. Its risks include volatility, irreversible transfers, wallet security, network fees, fraud, and changing legal requirements.
The safest approach is practical rather than promotional: use a clear contract, choose the asset and network carefully, protect wallet credentials, keep complete records, and obtain professional advice when tax or regulatory questions arise. Blockchain can be a useful payment rail, but good contracts, secure processes, and clear communication remain the foundation of a successful freelancer-client relationship.
Israel Otoijamun is the founder of Xcrow, an AI-powered freelance marketplace connecting businesses with remote professionals. He has over 15 years experience in digital business, freelancing, technology, and online platforms. He writes about freelancing, remote work, hiring, digital payments, and the future of online work.